What more than a century of market history says about the money you keep in cash, and what it does not say.
1. The number behind the argument
Here is the question almost every person near retirement is really asking: is the stock market a real thing, or did America just get lucky for a hundred years?
Three researchers have spent decades answering it. Elroy Dimson, Paul Marsh, and Mike Staunton built the data set. It now covers 35 markets going back to 1900,2 and it is published each year with UBS and London Business School.
The answer, in three numbers for the world index, in U.S. dollars:
| What you owned | Real return per year, 1900–2024 | What that has meant (Rule of 72) |
|---|---|---|
| Stocks | 5.2% | Buying power doubled about every 14 years |
| Bonds | 1.7% | Buying power doubled about every 42 years |
| Cash (Treasury bills) | 0.5% | Buying power doubled about every 144 years |
Source: Global Investment Returns Yearbook 2025.1 “Real” means after inflation has been taken out. It is what your money can actually buy, not what the statement says. These figures are based on historical market data over the periods studied and are provided for educational purposes only. Past performance does not guarantee future results.
Read the cash line again. Half a percent a year. At that historical rate, a 61-year-old would need to live past 200 for cash to double his buying power.
The point is not that stocks are exciting. It is that 5.2% and 0.5% are not two flavors of the same thing. They are two different outcomes for your last 30 years.
2. “But America got lucky”
This worry is fair, and it is not dumb. It has a name: survivorship bias.
Think of it this way. Imagine you want to know if hard work leads to a championship. So you interview every player on the team that won. They all worked hard, so you decide hard work wins championships. You never talked to the 29 teams that worked just as hard and lost.
That is the fear about American stock returns. We might be studying the one country that won, and calling it a law of nature.
The way to test that fear is to look at the losing teams too. The Yearbook tracks 35 markets, not one,3 and it separates the 21 with unbroken histories since 1900 from the markets whose records were interrupted.
Here is what they found when they did. The 2026 edition says stocks were the best-performing asset class in all 21 Yearbook countries with continuous investment histories, and that bonds beat bills in every one of those countries except Portugal.4
Not only in the winners. In every market with an unbroken record since 1900. The markets that closed outright are a different story, and I cover them in section 5.
Not a list of peaceful places
Most people skim past this. The 35 markets include countries that lost world wars, got occupied, got rebuilt out of rubble, and printed their money into confetti. Germany. Japan. Austria. France. Italy. These are not 35 versions of Ohio.
Businesses kept making things and selling them. Over long enough stretches, the people who owned those businesses got paid. In my view that is not luck. It is what owning productive businesses has tended to do over long periods, with long, painful stretches along the way.
3. Why 5% is bigger than it sounds
Five percent sounds boring. It is not, because it compounds.
There is a shortcut for this called the Rule of 72. Divide 72 by your yearly return, and you get the rough number of years it takes to double. At 5.2%, that is about 14 years. Run it for cash at 0.5%, and you get 144 years.
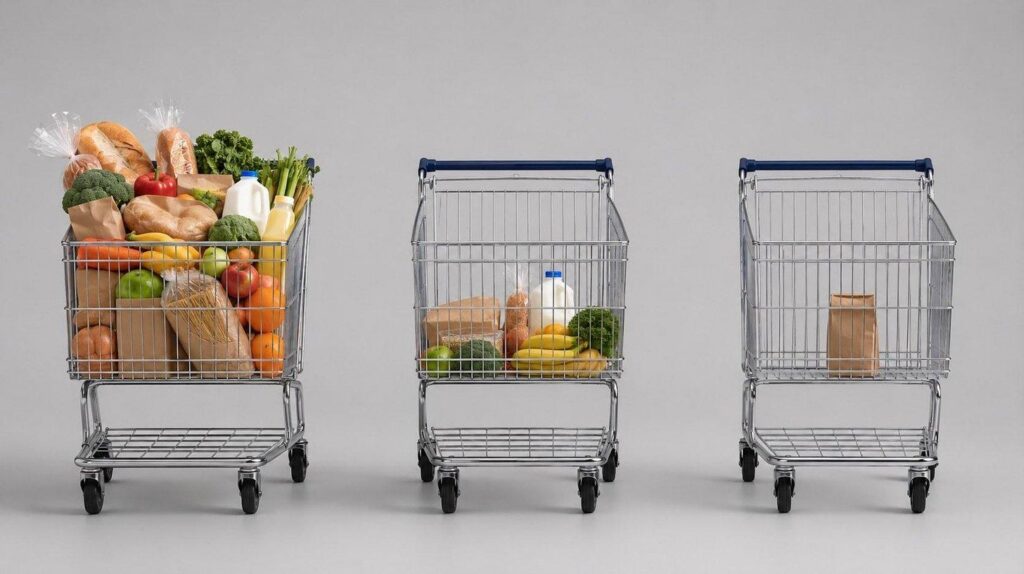
Picture a shopping cart instead of a bank statement. Fill it with what $50,000 buys today. At the stock market’s long-run historical rate, in 14 years you would have had two carts. In 28 years, four. Same cart, same groceries, four times as many of them.
Now do cash. In 14 years you have one cart and a bag. Wait 28 years, and you have one cart and two bags. The second cart never arrives.
| Real return | After 14 years | After 30 years | Doubling time |
|---|---|---|---|
| 5.2% (stocks) | About 2x | About 4.6x | ~14 years |
| 1.7% (bonds) | About 1.3x | About 1.7x | ~42 years |
| 0.5% (cash) | About 1.1x | About 1.2x | ~144 years |
Multiples are of buying power, not dollars. Illustration of compounding at historical rates, not a forecast; nobody earned these rates in a straight line. Math run at the long-run real rates reported in the Yearbook.
Thirty years is not a made-up number. A 65-year-old man is expected to live about 18 more years, and a 65-year-old woman about 21.8 Those are averages, and many people live longer. For a couple, the odds that at least one of you is still here at 90 are not small. You are not investing for 10 years. Your money is working for someone who might still be here in 2056.
4. What cash is doing to you right now
The 0.5% figure covers 125 years. Some people hear it and think, sure, but rates are good now. Let’s check.
A 3-month Treasury bill yielded 4.24% on September 25, 2026.7 Prices went up 3.4% in the 12 months through August 2026.6 Subtract one from the other, and you get about 0.8% ahead, before taxes.
Then taxes take a cut. Treasury bill interest is taxed as ordinary income at the federal level, though it is exempt from state and local income tax. In the 22% federal bracket, 4.24% becomes about 3.31% after tax, a little under 3.4% inflation. In the 12% bracket you stay about 0.3% ahead. In higher brackets you fall further behind. The chair is comfortable. It is not moving you forward much, and for many savers it is moving them back.
Here is the trap. Cash feels safe because the number on the statement never goes down. It goes down anyway, just never on the statement. The loss shows up at the grocery store, at the pharmacy, at the mechanic. A slow leak in a tire does not look like a flat. You just notice, a few years later, that the ride got rough.
If inflation ran at 3.4% a year for 30 years, an assumption, not a forecast, a dollar parked today would buy about 37 cents worth of groceries at the end. Nothing on your statement would tell you that happened.
5. The catch that often gets skipped
I am not going to hand you an average and pretend the average happened to everybody. It did not.
Some markets went nowhere for a very long time
Japan’s Nikkei hit 38,915.87 on December 29, 1989. It did not close above that level again until February 22, 2024.9 That is 34 years and 2 months. That count is the index price alone; counting dividends would shorten the wait somewhat, and the price index alone does not show by how much. Either way, someone who put everything into Japanese stocks at the 1989 peak waited a very long time to get back to even.
Some records end abruptly
Not every market made it through the century in one piece, which is why the Yearbook’s “continuous investment histories” qualifier matters. Russia is the classic case. After the 1917 revolution, the new government declared every loan from the old government invalid10 and stopped paying. Dutch investors alone lost an estimated 1 to 2 billion guilders, and they never received any return.
And cash has been destroyed completely, more than once
Before World War I, a dollar bought 4.2 German marks. By November 1923, a dollar bought 4.2 trillion marks.11 The mark lost about a trillion-fold against the dollar in under a decade.
A story that circulated in Berlin at the time says it better than any chart. A woman went shopping carrying her cash in a basket. She set the basket down for a minute. When she turned around, the basket had been stolen and the money left behind.12
That is the honest version of the story. One country can go nowhere for 34 years. A currency can go to nothing. In my view, both of those facts argue for spreading your ownership out, and neither one argues for sitting in cash.
6. So which dollars belong in stocks?
None of this means you empty your savings account tomorrow. Money you are going to spend soon has no business in the stock market, and the reason is not fear. It is arithmetic.
When a bad year hits, and you have to sell shares to pay your bills, you lock the loss in. You are selling the car for parts to buy gas. The math on this is brutal and well documented.
U.S. Bank ran the illustration. Two retirees, both with $1,000,000, both pulling out $45,000 a year and raising it 3% for inflation. Both got the exact same four returns: +25%, +10%, +5%, and -15%. The only difference was the order.
| Retiree | Order of returns | How long the money lasted |
|---|---|---|
| Good years first | +25, +10, +5, -15 | About 40 years |
| Bad year first | -15, +5, +10, +25 | About 25 years |
Same returns. Same withdrawals. Fifteen years of difference, decided by the order the years happened to arrive in.13
You cannot control the order. What you can control is whether you are forced to sell into it. That is the whole job of the cash and bonds in a retirement plan. They are not there to grow. Their job is to make sure nothing forces your hand in a bad year.
The rough line I use: money you need inside five years does not belong in stocks. Money you will not touch for ten or more years generally should not sit in cash. The middle is a judgment call, and it depends on your spending, not on the news.
This framework depends on your other income, your spending flexibility, and how you handle a falling market. Someone with a pension that covers most of the bills may need less in cash. Someone with a large, lumpy expense coming, or who would sell in a panic, may need more. It is a general framework, not a recommendation for your situation.
| When you need it | Where it belongs | Why |
|---|---|---|
| 0–5 years | Cash, T-bills, short bonds | It must be there on the day you need it, whatever the market did |
| 5–10 years | A mix, leaning toward bonds | Time to recover from a bad stretch, but not a lot of it |
| 10+ years | Stocks, spread out | This money needs to outpace inflation over time; historically stocks have done that more often than bonds or cash, with large drops along the way |
7. What I told a client who wanted out
Names, ages, dollar amounts, and identifying details in every client story today have been changed, and some stories are composites of more than one family. The decisions and the words are real.
I hear a version of this worry from people I meet all the time. One client, an American living in France, told me he was thinking about moving his money out of United States stocks altogether. Geopolitics worried him. So did a few other things.
I told him that was a fair question, and then I walked him through the numbers in this post. The 2026 Yearbook also tested whether a rising geopolitical threat index predicted world stock returns a month or a year ahead, and found no relationship. The exceptions were the rare events with real economic damage: the two world wars and the 1973–74 oil shock, three of the six worst episodes for large global stock markets since 1900. He decided to keep his allocation where it was. That is one person’s decision, not a typical result, and not a recommendation for yours.
The trade-off is real either way. Cash spares you the bad years and charges you the growth. Stocks pay for the growth with crashes and long flat stretches. Which one costs you more depends on when you need the money.
The lesson from 125 years is not that stocks always go up. They do not. The lesson is narrower and more useful: owning good businesses, spread out, for a long time, has rewarded patient people in every market with a continuous record in the Yearbook, with long, ugly waits along the way. That is a smaller claim than the market usually makes, and in my view it is the one the evidence supports.
That is why, in the portfolios I help manage through Savvy Advisors, I favor a focused group of what I would call great businesses, companies with durable competitive advantages and managers who think like owners, rather than betting everything on one name or one nation. Concentration is a choice with its own risk: a focused portfolio can trail a broad index for long stretches, and a few bad picks hurt more. That is a general description of an approach, not a recommendation for your situation.
A second set of eyes on your own numbers
The question that actually matters is not “are stocks good.” It is “which of my dollars belong where, given when I am going to spend them.” That answer is different for every household, and it is not something you should get from a blog post.
If you want to walk through your own numbers, book a free consultation here. No pitch, no product. We look at what you have, when you need it, and where the line falls for you.
More writing like this is at the Berk on Value blog.
Notes
- Cambridge Judge Business School report on the Global Investment Returns Yearbook 2025, giving real annualized 1900–2024 returns of 5.2% for world equities, 1.7% for bonds, and 0.5% for bills across 35 markets. https://www.jbs.cam.ac.uk/2025/report-stocks-have-far-outperformed-over-the-past-125-years/ ↩
- UBS media release for the Global Investment Returns Yearbook 2025, March 4, 2025, covering the 35-market count. https://www.ubs.com/global/en/media/display-page-ndp/en-20250304-global-investment-returns-yearbook-2025.html ↩
- UBS Global Investment Returns Yearbook 2026, Public Summary Edition, p.4: annual return data across 35 markets, 126 years since 1900. https://www.ubs.com/global/en/media/display-page-ndp/en-20260303-global-investment-returns-yearbook-2026.html ↩
- UBS Global Investment Returns Yearbook 2026, Public Summary Edition (Dimson, Marsh, Staunton), p.7: equities the best-performing asset class in all 21 Yearbook countries with continuous investment histories; bonds beat bills in every country except Portugal. p.11: no relationship between a geopolitical threat index and world equity returns one month or one year ahead; WWI, WWII and the 1973–74 oil shock among the six worst episodes. UBS media release, March 3, 2026: https://www.ubs.com/global/en/media/display-page-ndp/en-20260303-global-investment-returns-yearbook-2026.html ↩
- Investment Company Institute weekly money market fund assets release: $7.94 trillion total and $3.11 trillion retail for the week ended September 23, 2026 (released September 24, 2026). https://www.ici.org/research/stats/mmf ↩
- U.S. Bureau of Labor Statistics Consumer Price Index Summary for August 2026, released September 11, 2026: all-items CPI-U up 3.4% over 12 months before seasonal adjustment, core up 2.4%. https://www.bls.gov/news.release/cpi.nr0.htm ↩
- Federal Reserve Bank of St. Louis (FRED) series DGS3MO, market yield on 3-month U.S. Treasury securities at constant maturity: 4.24% on September 25, 2026. https://fred.stlouisfed.org/series/DGS3MO ↩
- Social Security Administration Period Life Table, 2023 (as used in the 2026 Trustees Report): 18.12 years remaining life expectancy for males at exact age 65, 20.66 years for females. https://www.ssa.gov/oact/STATS/table4c6.html ↩
- Nippon.com, on the Nikkei 225 closing at 39,098.68 on February 22, 2024, finally passing the 38,915.87 record set December 29, 1989, 34 years and 2 months later. Index price level; dividends not included. https://www.nippon.com/en/japan-data/h01927/ ↩
- Exchange History (Amsterdam), on the 1917 Soviet repudiation of tsarist-era securities and the 1 to 2 billion guilder loss to Dutch investors, who were never compensated. https://www.beursgeschiedenis.nl/en/moment/russian-securities-declared-invalid/ ↩
- Princeton (Brunnermeier) teaching materials on the German hyperinflation: 4.2 marks per dollar before World War I, 4.2 trillion marks per dollar by November 1923, the exchange-rate collapse of the mark. https://markus.scholar.princeton.edu/sites/g/files/toruqf2651/files/documents/German_Hyperinflation1919_23.pdf ↩
- Econlib, “Hyperinflation in Germany, 1921–1923,” including a story circulating in Berlin in 1923 of a stolen basket of cash. https://www.econlib.org/hyperinflation-in-germany-1921-1923/ ↩
- U.S. Bank, “Sequence of returns risk and impact on when to retire”: two $1,000,000 portfolios with identical returns in different order and $45,000 inflation-adjusted withdrawals lasted about 40 years versus about 25 years. https://www.usbank.com/retirement-planning/financial-perspectives/sequence-of-returns-risk-impact-when-to-retire.html ↩
- UBS Investment Bank Yearbook 2025 landing page: of the 35 markets covered, 23 have 125-year histories from 1900 to 2024. (The 2026 edition counts 21 with continuous investment histories; this post uses the 2026 count.) https://www.ubs.com/global/en/investment-bank/insights-and-data/2025/global-investment-returns-yearbook-2025.html
Important Disclosures
These figures are based on historical market data over the periods studied and are provided for educational purposes only. Past performance does not guarantee future results.
This content was created with the assistance of third-party artificial intelligence and was reviewed and approved by David Berkowitz prior to publication.
If this post appears alongside the companion video: Heads up: I make this content free so you never have to pay for the ideas in it. The presenter you see is an AI-generated avatar of me, David Berkowitz, produced with HeyGen. I write and approve every script, and I personally read and reply to the comments, so ask me anything below. This video is general education, not personalized investment, legal, or tax advice, and nothing here creates an advisory relationship. This content was created with the assistance of third-party artificial intelligence and was reviewed and approved by David Berkowitz prior to publication. Full disclosures below.
This content is produced by David Berkowitz under ValueAligned Partners, LLC, DBA VAP Wealth Advisors (“VAP Wealth Advisors”), an independent marketing brand, and is provided for general educational and informational purposes only. It is not, and should not be construed as, personalized investment, legal, tax, or accounting advice, nor an offer or solicitation to buy or sell any security.
No advisory relationship. Viewing, reading, or interacting with this content does not create an investment-adviser, attorney-client, or accountant-client relationship. David Berkowitz is an investment adviser representative registered with Savvy Advisors, Inc. (“Savvy”), and all investment advisory services he provides are offered through Savvy. Investment advisory services are offered only through a written agreement with Savvy. ValueAligned Partners, LLC, DBA VAP Wealth Advisors, is an independent marketing brand used for advertising and marketing purposes only; ValueAligned Partners, LLC and Savvy are not related or affiliated. Additional information is available in Savvy Advisors’ Form ADV Part 2A and Form CRS at adviserinfo.sec.gov.
Not legal or estate-planning advice. David Berkowitz is not an attorney, and VAP Wealth Advisors does not practice law, draft legal documents, or provide legal opinions. Any discussion of wills, trusts, powers of attorney, beneficiary designations, or other estate-planning topics is general education only. You should consult a licensed attorney in your state before drafting, signing, or relying on any estate-planning document.
Not tax or accounting advice. David Berkowitz is not a CPA or Enrolled Agent, and VAP Wealth Advisors does not prepare tax returns or provide tax-return preparation services. Any discussion of tax topics is general education intended to help you understand tax-planning concepts and coordinate with your CPA or tax preparer. You should consult a qualified tax professional regarding your specific situation before acting on anything discussed here.
No guarantees; investment risk. All investing involves risk, including possible loss of principal. Past performance is not indicative of, and does not guarantee, future results. Forward-looking statements are opinions as of the date recorded and are subject to change without notice.
Sources and third-party content. Links, tickers, and third-party materials are provided for convenience and do not constitute an endorsement. VAP Wealth Advisors is not responsible for the content of third-party sites.
Positions. David Berkowitz, his clients, employees, and family may own the stocks mentioned in this content. He is under no obligation to update the content or to disclose any future purchases or sales of those stocks.
All advisory services are offered through Savvy Advisors, Inc. (“Savvy Advisors”), an investment advisor registered with the Securities and Exchange Commission (“SEC”). Savvy Wealth Inc. (“Savvy Wealth”) is a technology company and the parent company of Savvy Advisors. Savvy Wealth and Savvy Advisors are often collectively referred to as “Savvy”.
David L Berkowitz is an investment advisor representative registered with Savvy Advisors, Inc. (“Savvy”). All investment advisory services offered by David L Berkowitz are offered through Savvy. ValueAligned Partners, LLC (also doing business as VAP Wealth Advisors) is an independent marketing brand name used by David L Berkowitz for advertising and marketing purposes only. ValueAligned Partners, LLC and Savvy are not related or affiliated. For more information about Savvy, please visit our website at savvywealth.com/advisor.